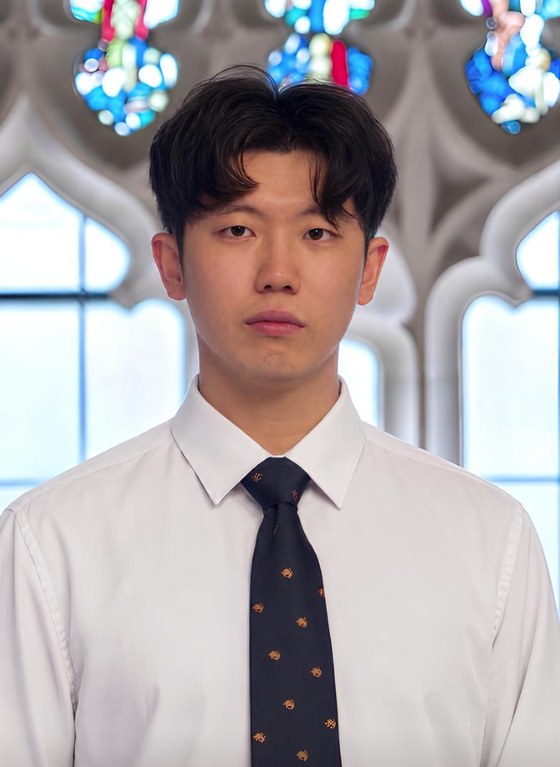
I am a Research Professional at the Becker Friedman Institute for Economics at the University of Chicago, where I work with Chang-Tai Hsieh and Erik Hurst. I received a B.A. in Economics and Statistics from the University of Chicago. My research is broadly within economics and finance.
My CV is available here. My email address is giyoung@uchicago.edu.
Working Papers
Addiction Runs: Rank Competition and Strategic Complementarities in Prescription Stimulant Usage
(with Chanwool Kim and Younggeun Yoo)
Presentations: Workshop in Behavioral and Experimental Health Economics (2026, Scheduled)
Draft available upon request.
Abstract
We study the rise of prescription stimulant use for academic performance using a model with relative-performance externalities. Students compete for rank, where taking a stimulant improves effective performance but entails costs. Because payoffs from academic competition depend on others' performance, students' stimulant usage exhibits strategic complementarities: as more individuals use stimulants, others face stronger incentives to follow in order to avoid falling behind. We identify the model using prescription trends in the U.S. and our own survey evidence on students' incentives, beliefs, and perceived costs. The estimated strategic complementarities are large enough to generate multiple equilibria, including one with low use and another with very high use, in which around 90 percent of students take stimulants. We use the estimated model to evaluate policies that (i) reduce the salience of relative evaluation, (ii) limit the competitive advantage conferred by stimulants, particularly through academic accommodations, (iii) separate academic competition between stimulant users and non-users (i.e., separate curves), and (iv) tighten prescribing standards to reduce non-medical use. Our estimates show that separate curves yield rankings that most closely reflect underlying ability and are the policy that least discourages true ADHD patients from taking prescribed stimulants.
The Cost of Leverage: Retail Demand and Option Prices
(with Jingoo Kwon, Seung Hyeong Lee, Seongkyu Gilbert Park, Younggeun Yoo, and Haesung Kim)
Presentations: Conference on Asia-Pacific Financial Markets (2026, Scheduled)
Draft available upon request.
Abstract
Retail investors often use options to obtain leveraged exposure. Using account-level administrative data covering the universe of KOSPI 200 index option trades from 2010 to 2014, when Korea hosted one of the world’s largest options markets, we examine how retail demand shapes option prices and investor performance. Retail investors buy to open more than 80% of their positions in both calls and puts, concentrating their purchases in short-dated, out-of-the-money options. This buying tendency is highly persistent at the investor level and more consistent with demand for leverage than with directional views or capital constraints. Options with greater retail demand exhibit higher implied volatility but not higher subsequent realized volatility, indicating larger risk premia. This pricing relationship is strongest for out-of-the-money options: a one-standard-deviation increase in retail demand corresponds to an estimated price increase of 3.8-4.3%, compared with 0.3-0.5% for at-the-money options. We provide causal evidence for the role of retail demand by showing that implied volatility declined following an exogenous policy shock that reduced retail participation. As buyers bear these premia, buy-opened positions lose money on average for both retail and institutional investors, while sell-opened positions earn profits. Retail investors’ concentration on the buying side thus helps explain why 76% of retail accounts lose money, whereas more than 60% of institutional accounts earn profits. These findings reveal a hidden cost of leverage: retail investors’ collective demand raises the price of the leveraged exposure they seek and contributes to their trading losses.